
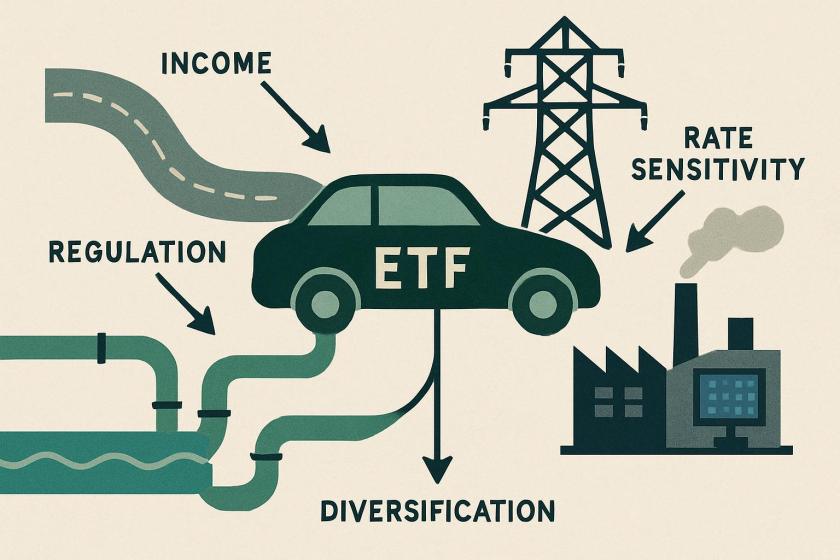
Infrastructure exposure can look deceptively simple until you examine what counts as “infrastructure.” Some funds stay close to the classic trio of utilities, energy and transport, while others widen the lens to owners of hard assets, regulated cash flows and toll-like economics. That distinction matters for ETF investors because it changes sector concentration, valuation sensitivity and how closely the fund behaves like a pure defensive sleeve versus a broader growth-and-income allocation.
A broader mandate can improve diversification, but it can also dilute the portfolio’s identity. If an infrastructure ETF expands into more subsectors, the benefit is that it may capture multiple secular drivers at once, such as data-center buildout, grid modernization, logistics and demographic demand. The trade-off is that investors need to understand whether they are buying a narrow income proxy or a wider industrial-asset theme with more moving parts and potentially less sector purity.
Rate sensitivity is another key issue for long-term allocators. Infrastructure cash flows can be attractive in periods of economic stress, yet many holdings are still capital-intensive businesses that depend on financing conditions. That means the role of the ETF in a portfolio should be judged not only on income characteristics, but also on how it may respond to changing yields, refinancing needs and the market’s willingness to pay for stable cash generation.
For investors building a core-satellite portfolio, the practical question is rebalancing discipline. Infrastructure can act as a stabilizer, but only if its weight is monitored relative to other defensive assets such as utilities, dividend equities or bonds. The case for the category is less about short-term timing and more about whether the underlying asset base, regulation and demand profile still support a durable long-horizon allocation.
Infrastructure Investing: Why Now?
To begin, Rosenbluth asked Campbell why now could be an interesting time for advisors and investors to look at gaining infrastructure exposure. Campbell explained that infrastructure investing has historically been able to provide portfolios with income, along with downside protection, which are two things many investors and advisors are looking to expand upon within their portfolios. Furthermore, Campbell noted that the global space is benefiting from a menagerie of favorable tailwinds. “Things like artificial intelligence, globalization, reshoring, friend-shoring, nearshoring — whatever you want to call it, Todd. They’re all impacting infrastructure,” Campbell added. “And then things as old as demographic trends. We are on the cusp of a massive demographic change, and we think infrastructure is going to have a big role to play in that.”BKGI Brings a Broader Approach to Infrastructure Investing
Moving on, Rosenbluth pivoted his focus to BKGI. He asked Campbell about the fund’s strategy and how it stands out from other infrastructure funds in the field. Campbell explained that BKGI seeks to offer a different take on infrastructure investing in part through a broader opportunity set. He elaborated that many traditional infrastructure strategies focus on three industries: utilities, industrials, and energy. BKGI differentiates itself from these funds by applying a different definition of what infrastructure companies are. The BNY Investments team uses its own definition of infrastructure to look beyond those three traditional industries. “We believe that infrastructure are companies that have fixed assets in the ground, are earning rent or cash flow off those assets, and have a great deal of regulatory predictability,” Campbell explained. This wider opportunity set allows BKGI more bandwidth to tap into momentum from different secular themes, as Campbell noted. These themes include aging demographics, the AI build-out, and more.How BKGI Fits Into a Portfolio
Looking closer at BKGI, Rosenbluth then asked Campbell how investors should look to fit BKGI into their portfolios. Campbell explained that the fund is generally focused on delivering income along with downside protection. He elaborated that infrastructure companies as a whole tend to be less sensitive to shifting economic conditions. On paper, these companies tend to offer better performance during economic weakness than other sectors. Furthermore, Campbell noted that if stagflation does play out, infrastructure companies could be in a better position to perform compared to other stocks. This is because, as Campbell explained, these companies can more easily pass costs on to their consumer base. “When there’s economic concern or a lower economic cycle, these are resources and consumption that doesn’t change based on how the economy is doing,” Campbell added. “Think of water consumption or your electricity consumption or how much Netflix you are streaming. That doesn’t change during a cyclical downturn, but you still need the pipes delivering those.”Enjoyed this article? Sign up for our newsletter to receive regular insights and stay connected.