
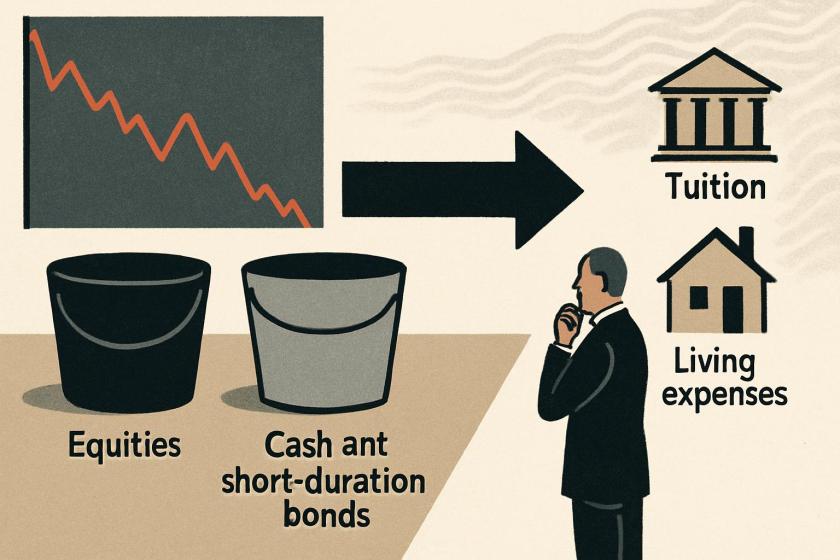
Retirement spending is an allocation decision, not just an income decision. When portfolio withdrawals begin, the key question is not whether a nest egg is large on paper, but how much of it must be exposed to market swings while near-term spending is being funded. For ETF investors, this shifts attention from total return chasing to the design of the income bucket and the refill process behind it.
One useful lens is time horizon matching. Cash, short-duration bonds, and higher-quality fixed income can serve as a reserve for planned withdrawals, tuition, or other known expenses, reducing the need to sell risk assets during weak markets. That is especially relevant when spending needs are front-loaded or unpredictable. The point is not to eliminate equity exposure, but to separate money needed soon from money meant to compound over longer periods.
Another overlooked issue is flexibility. A withdrawal policy that can move modestly with markets, spending changes, or a spouse’s earned income is often more resilient than a rigid formula. For long-term investors, that means reviewing not only the withdrawal rate but also where the cash will come from if equities fall, inflation stays sticky, or a large one-time expense appears.
ETF portfolios should therefore be judged by structure, not just labels. A mix of broad equity funds, defensive bond exposure, and liquidity reserves can support retirement behavior as much as it supports returns. The practical goal is to avoid forced selling, preserve optionality, and keep spending decisions aligned with the portfolio’s actual risk profile.
Key Points
- A 3% withdrawal rate on $3.6M generates $108K annually with a 95% success rate over 30 years.
- The retiree left a $145K salary but faces significant college costs ahead.
- Their working spouse maintains a seven-figure retirement plan and could continue earning for 5 to 10 years.
- If you’re focused on picking the right stocks and ETFs you may be missing the bigger picture: retirement income. That is exactly what The Definitive Guide to Retirement Income was created to solve, and it’s free today. Read more here
Key Points
- A 3% withdrawal rate on $3.6M generates $108K annually with a 95% success rate over 30 years.
- The retiree left a $145K salary but faces significant college costs ahead.
- Their working spouse maintains a seven-figure retirement plan and could continue earning for 5 to 10 years.
- If you’re focused on picking the right stocks and ETFs you may be missing the bigger picture: retirement income. That is exactly what The Definitive Guide to Retirement Income was created to solve, and it’s free today. Read more here
Enter the case of a 61-year-old new retiree
In this piece, we look at a 61 year old retiree who recently left behind a $145,000 salary. They have built a strong financial foundation, including nearly $2 million in a 401(k), healthy balances in other tax advantaged accounts, and a sizable amount of cash and CDs. With solid investments and plenty of liquidity, they appear to be well prepared for a long retirement. Their spouse, age 55, is still working and contributing to a seven figure retirement plan as well. On paper, this couple seems to have little reason to worry about running out of money unless they plan to dramatically elevate their lifestyle during retirement. The real pressure point is the significant cost of their child’s upcoming college years. Tuition and related expenses can snowball quickly, especially if the child pursues advanced degrees. Fortunately, the retiree has enough liquidity in cash and CDs to fill any gaps that might remain after using the funds in the 529 plan. Given the likelihood of market volatility as tariff concerns continue through spring and possibly into the summer, it would be wise to avoid tapping the portion of the portfolio invested in stocks. With major education costs ahead and a natural fear of draining funds too quickly, a conservative withdrawal rate is the safer approach. As always, a financial advisor can help tailor the strategy based on goals, risk tolerance, and long term comfort.What’s a good withdrawal rate to target?
The 4 percent rule is one of the most widely used guidelines for retirees. It suggests withdrawing 4 percent of the initial portfolio in the first year of retirement and then adjusting that amount each year for inflation. With roughly $3.6 million in investable assets, a classic 4 percent withdrawal rate would produce close to $145,000 per year, which is more than enough to support a very comfortable retirement. Given rising market volatility and significant upcoming college expenses, leaning toward a 3 percent withdrawal rate is likely the safer path. This retiree is already positioned conservatively with a large amount in cash and CDs, which suggests a lower risk tolerance and a strong desire to avoid running out of money. A 3 percent withdrawal rate on a $3.6 million nest egg provides about $108,000 per year, which is still a substantial income. Historically, a 3 percent withdrawal rate has been considered very conservative, with long term simulations showing a success rate above 95 percent for a 30 year retirement, even in difficult markets. A financial advisor can help determine the right withdrawal rate based on spending expectations and personal comfort. If annual expenses fall well below $108,000, there is room to withdraw even less. A range between 2.5 and 3.0 percent seems very reasonable. The good news is that the retiree’s spouse is still working and likely can continue for another 5 to 10 years. If the market falters or college costs rise more than expected, the option to keep working remains available. Overall, this retiree appears to be in strong financial shape, with enough flexibility to adopt a conservative withdrawal strategy and enjoy real peace of mind throughout retirement.The bottom line
Remember, a withdrawal rate isn’t set in stone! In fact, adjusting it on the fly based on the environment or expectation for large expenses could be the way to go. If stocks are reeling and tuition expenses are coming due, a lower withdrawal rate can make sense. It can always be increased later on (towards 4%) once one’s comfort level improves.Released: The Ultimate Guide To Retirement Income (sponsor)
Most investors spend years learning how to pick good stocks and funds. Far fewer have a clear plan for turning those investments into a reliable retirement paycheck. The truth is, the transition from “building wealth” to “living on wealth” is one of the most overlooked risks facing successful investors in their 50s, 60s and 70s.Enjoyed this article? Sign up for our newsletter to receive regular insights and stay connected.