
S&P U.S. Indices Mid-Year 2023: Analyzing Relative Returns To CRSP

For ETF investors, the key lesson is not that one U.S. equity benchmark is “better” than another, but that similar-sounding indexes can carry meaningfully different exposure maps. When an ETF tracks an index that weights sectors, size tiers, or reconstitution rules differently, the portfolio can diverge from a competing benchmark even when both are marketed as broad U.S. equity exposure. That divergence matters most when a narrow leadership theme dominates market returns.
In this case, the relevant portfolio tension is concentration. A benchmark with a smaller technology weight, or different rules for including mega-cap names, may lag when a handful of large growth stocks lead the market; the reverse can happen when leadership broadens or rotates. For investors, that means relative performance can reflect construction choices as much as stock selection or “market quality.”
This also highlights why style labels deserve a closer look. Value and growth ETFs, for example, may appear comparable across index families, yet different eligibility screens and rebalancing rules can tilt one fund toward more technology and another toward less. Over time, those differences can change sector concentration, tracking behavior, and the investor’s real factor exposure.
A practical takeaway is to evaluate the index first, then the ETF wrapper. Before choosing between funds, compare the benchmark methodology, top holdings concentration, and how often constituents change. For long-term asset allocation, the most important question is whether the fund’s built-in exposures match the role you want it to play in the portfolio.
lovelyday12/iStock via Getty Images
By Cristopher Anguiano
Following a challenging 2022, H1 2023 hosted a recovery among
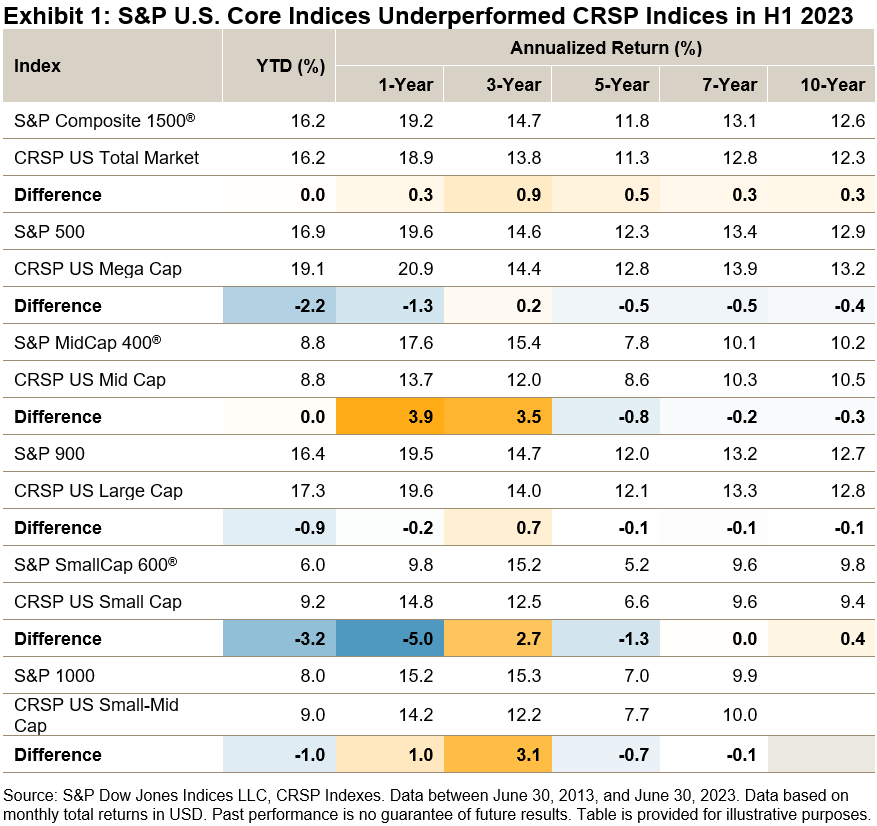
equities: the S&P 500® (up 16.9%) posted its fourth-best first half since 1996, and there were gains across the market cap spectrum. But on a relative basis, and in contrast to longer horizons, the S&P Core U.S. Equity Indices lagged their CRSP counterparts in H1 2023 (see Exhibit 1).
The informed reader knows that 2023 has been a strong year for mega caps and Information Technology companies. Indeed, the S&P 500 Information Technology (42.8%) and S&P 500 Top 50 (27.6%) posted their best first-half performance since 1996 (see Exhibit 2). Given that S&P DJI’s indices benefited from having less exposure to Information Technology in 2022, one might expect this helped to explain relative performance in H1 2023.
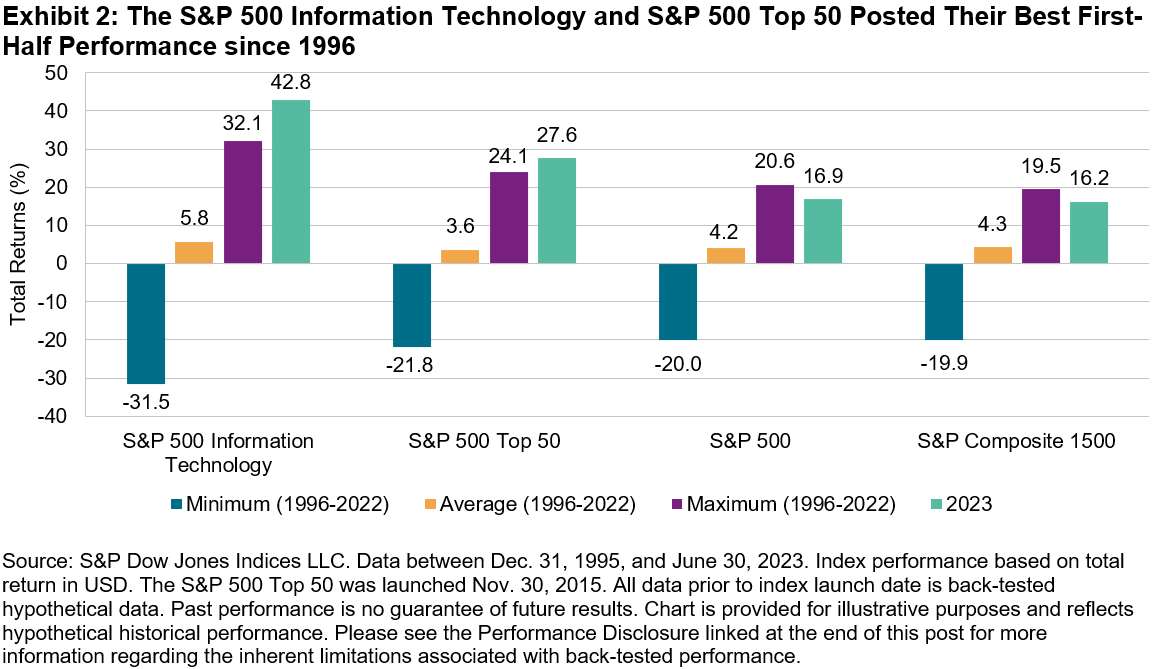
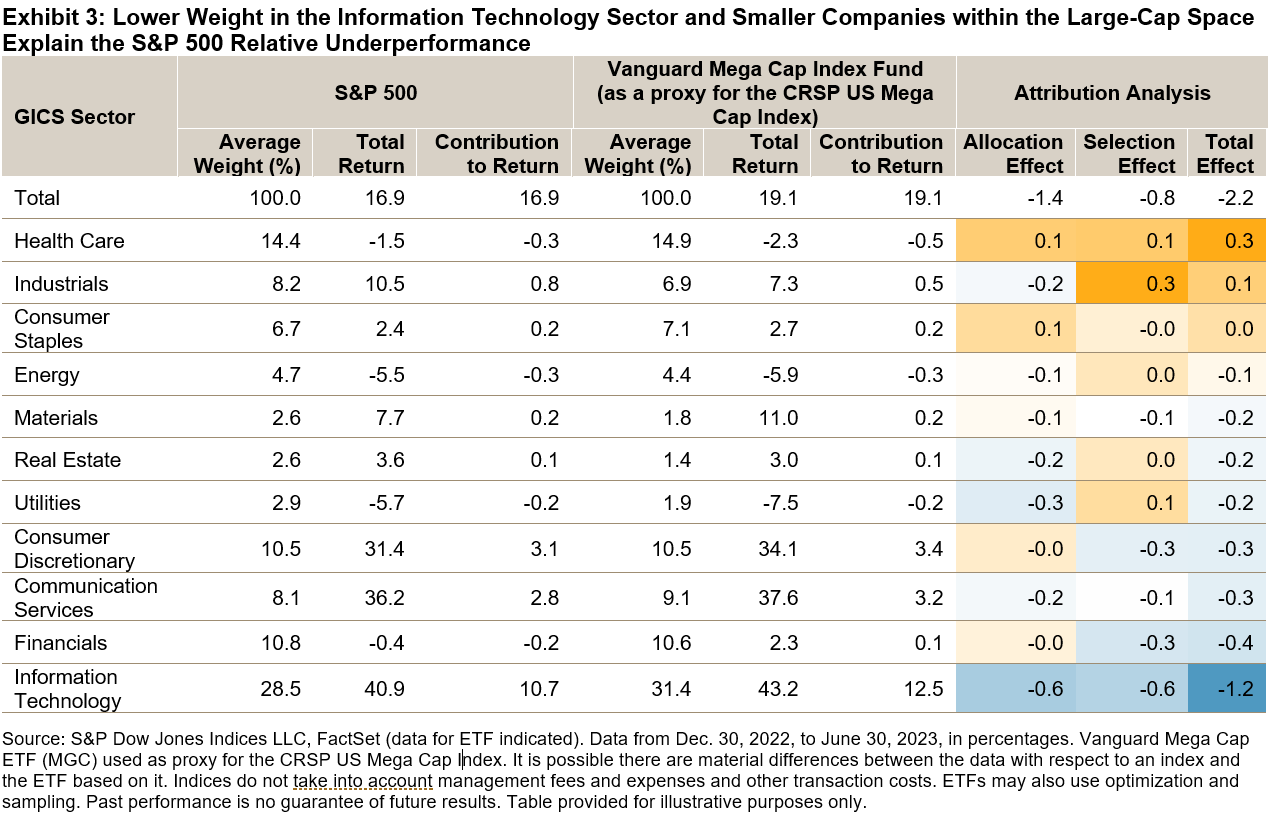
Exhibit 3 demonstrates that the S&P 500’s relative performance in H1 2023 was hindered by its lower weight in Information Technology. The Brinson attribution results show that less exposure to the Information Technology sector contributed negatively to the S&P 500 (-0.6%). Combined with the negative selection effect in Information Technology (-0.6%) – the S&P 500 and the CRSP US Mega Cap Index (as represented by the Vanguard Mega Cap Index Fund as a proxy) have different constituents owing to differences in index construction – likely around 50% of the S&P 500’s underperformance was attributed to Information Technology.
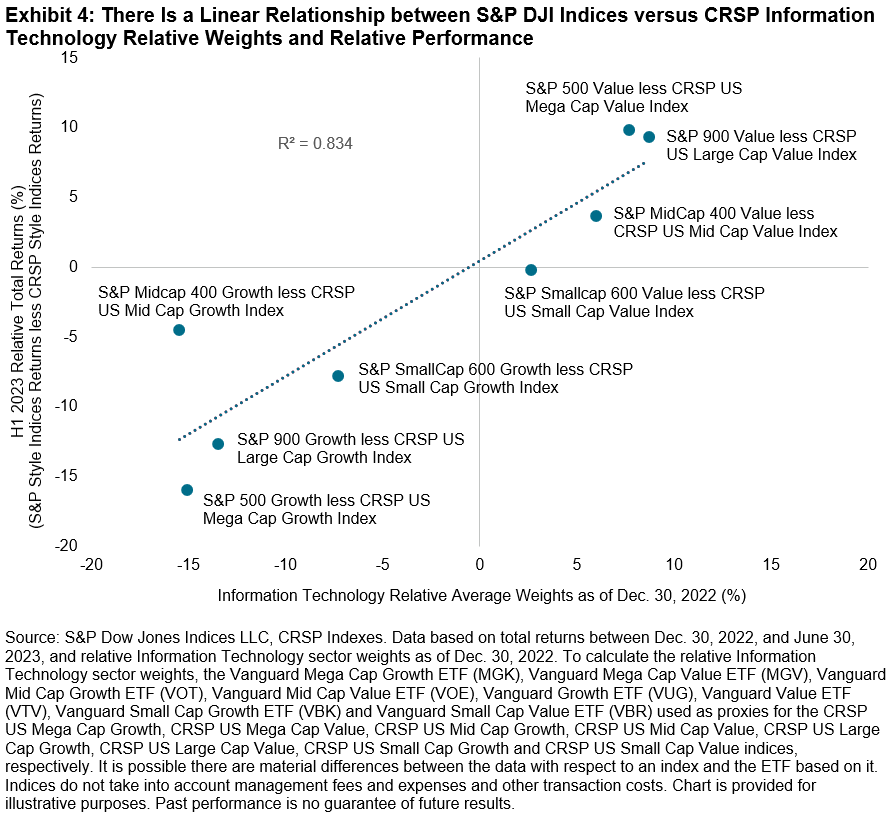
The consequences of Information Technology weight were even more apparent across style indices: Exhibit 4 shows that S&P Style Indices with more (less) exposure to Information Technology out- (under-) performed their CRSP counterparts in H1 2023. For example, the S&P 500 Value and S&P 900 Value posted their best relative H1 returns over the last 10 years, beating their CRSP counterparts by 9.9% and 9.3%, respectively. Conversely, the S&P 500 Growth and S&P 900 Growth posted their worst relative H1 returns over the same period, lagging their CRSP counterparts by 15.9% and 12.6%, respectively. Various CRSP index-based ETFs are used as proxies for the CRSP indices below.
The first half of 2023 once again highlighted the importance of index construction when assessing index characteristics, given different exposures can help to explain performance differences between indices with similar sounding objectives.
Disclosure: Copyright © 2023 S&P Dow Jones Indices LLC, a division of S&P Global. All rights reserved. This material is reproduced with the prior written consent of S&P DJI. For more information on S&P DJI, please visit S&P Dow Jones Indices. For full terms of use and disclosures, please visit Terms of Use.
Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.
Enjoyed this article? Sign up for our newsletter to receive regular insights and stay connected.