
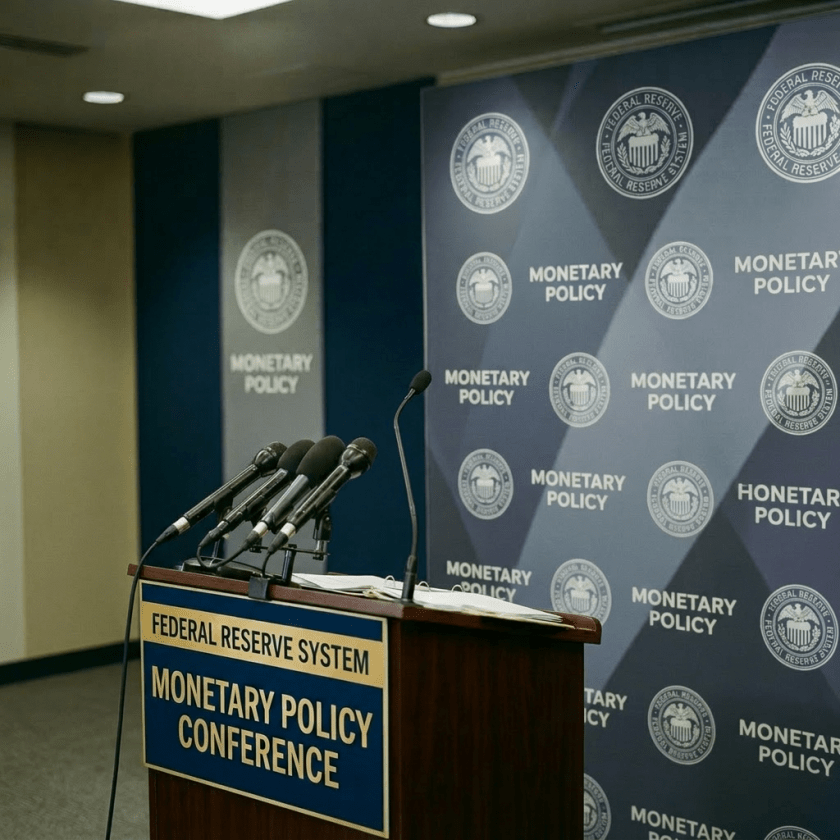
A new Fed chair can matter less for the headline rate path than for the framework behind it. For ETF investors, the important question is whether policy communication becomes more predictable, because clearer priorities can reduce the noise that often moves bond yields, equity multiples, and factor leadership. A central bank that signals its reaction function more cleanly can also make duration, credit, and equity risk easier to assess within a diversified portfolio.
That said, regime changes are usually interpreted over time, not in one meeting. Investors should watch three practical variables: how consistently the Fed emphasizes inflation, how much forward guidance it is willing to provide, and whether its internal review process changes the market’s confidence in policy execution. Those details affect more than Treasury prices; they shape the discount rate backdrop that ETF allocations across stocks, bonds, and multi-asset sleeves must absorb.
The portfolio implication is not to chase every policy headline. A rules-based allocation process can help separate durable shifts from temporary rhetoric. For long-term investors, that means focusing on asset mix, rebalancing discipline, and exposure concentrations rather than assuming one press conference changes the cycle on its own. When central-bank credibility improves, it may support steadier markets, but the investment job remains the same: keep the portfolio resilient across different inflation and growth outcomes.
There’s a new Sheriff in town. There’ll be some changes made, Kevin Warsh said in his first press conference as fed Chair. His tone was stern, crisp, and definitive. Between the 60% shortened FOMC statement, his pre-Q&A address, and his answers to the questions, the take-aways were clear: Focus on getting inflation to the 2% target (no, we’re not going to look at reevaluating that), very little or no forward guidance, less blathering, and taking a serious new look at several aspects of how the FOMC conducts its work.
His broader goals all can be taken as positive, in our view. Although he never used the words credibility or independence in his Chair debut with the press, these seemed to be the two main themes he was trying to get across in no-uncertain terms. Both of these concepts have been perennially debated by the Fed’s many evaluators and pundits over the years, and perhaps just as highly as ever in the last few. Some have said, and we would agree, that if you had to choose the two most important things the Fed cannot afford to lose, these are them. And although he did not explicitly link them, he went out of his way to stress that “This committee will deliver price stability” and the traditional importance of accountability for performance. Achieving this goal will require independence, and in doing so, will improve credibility. In the best of circumstances this could potentially nudge volatility and interest rates lower all else equal.
There were a few more subtle goals too. These were more related to the five task forces he is implementing. Maybe it could be summed up more glibly as, “Let’s be less hide-bound, shall we?” It’s an observation that can be leveled at any enormous bureaucratic organization, and the Fed is no exception. Notably, he said, “What we’ve given the markets is a new chapter for the central bank, some fresh thinking…” We think that this implies open-mindedness, innovation, and broader collaboration beyond just the Fed staff. His charge of “…start with first principles, ask hard questions, examine current practice, consider alternatives…” is a straightforward roadmap that has a good chance of yielding improvements.
The world is changing at an accelerating pace. Everybody knows this, of course. But surviving and thriving in this environment requires re-evaluation and change. The economic and corporate world, the free and wild commercial, capital and financial markets, have been adapting, evolutioning, and revolutioning remarkably quickly since the ChatGPT moment. We should all hope that the Fed will do so as well. This will be a work in progress, and it will take time to see what the effect is on the Fed’s ability to improve its performance, but again, success on this front should be positive for capital markets and economies in general.
What are the implications for Globalt’s investment process and strategy positioning? We believe that our weight of the evidence process is underpinned by continually executing on the same charge that Kevin Warsh outlined for his task forces. All of our strategies begin with our macro framework and the evaluation of the environment we are operating in, and how it is changing, where it is going. The markets react initially to new information and then constantly incorporate it over time. Our processes are structured with a goal of being successful over the longer-term using sound investment principles and is not geared toward short-term swings in perceptions. We are not changing the positioning in any of our strategies at this time but are prepared for change as a potential new chapter for the Fed unfolds.
RIP Alan Greenspan.
Enjoyed this article? Sign up for our newsletter to receive regular insights and stay connected.